Acorns Early: Kids Money App

Screenshots
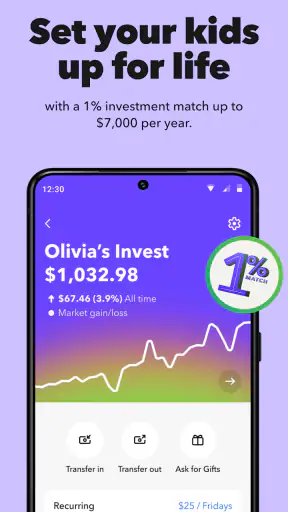
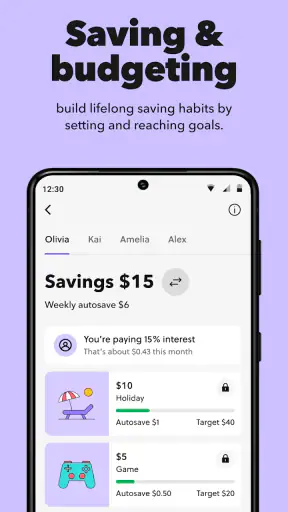
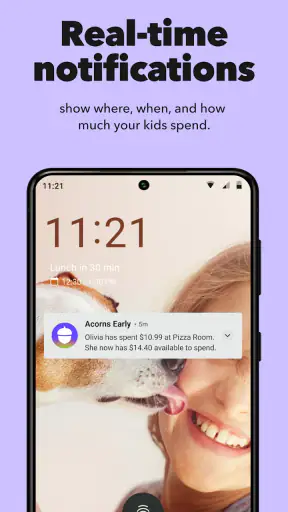
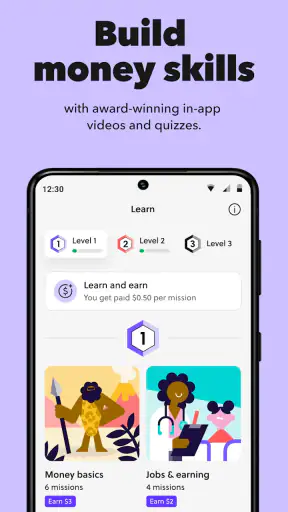
Details
- Rating
- 533.00 reviews
- Version
- 9.7.0
- Developer
- Acorns
Analysis by Norviv
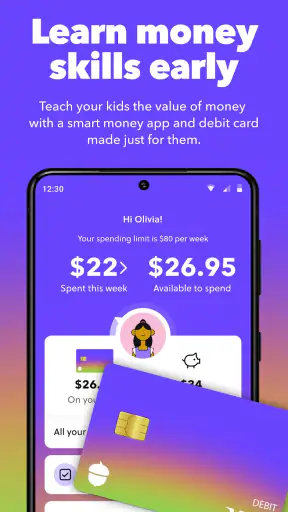
I approached Acorns Early as a parent-focused finance app rather than another brightly designed money game. Its purpose is to help families introduce saving and investing through a child’s financial setup, and that distinction matters. It is not trying to replace a full household banking service or teach every part of personal finance in one sitting. Instead, it gives parents a more structured way to start conversations about money and build repeatable habits around them.
The app comes from Acorns, a developer already associated with simple investing tools, and its focus here is younger users. The store summary describes a smart investing plan for kids and teens, while the short description identifies it as Acorns Early. In my experience, that positioning makes the app most useful when an adult stays involved and treats it as part of a family routine, not as an automatic solution to financial education.
It is free to install, carries an Everyone content rating, and supports Android 7.0 or later. The current version is 9.7.0, and the app was released on November 8, 2024. Those details make it accessible to a broad range of Android devices, although compatibility alone does not determine whether the experience will suit your family. The important question is whether you want a guided investing habit for a child or simply a place to track pocket money.
How the everyday workflow feels for a parent
The most sensible starting point is to think in terms of a parent-led workflow. I would begin by deciding what the child is meant to learn: the difference between saving and investing, the value of regular contributions, or the idea that money can have a longer-term purpose. That decision should come before opening settings, because the app works better when the family agrees on the habit it is trying to support.
A practical routine might be to review the account together once a week. The parent checks the plan, explains what has changed in plain language, and connects the discussion to a real goal, such as future education or a larger purchase. The child does not need a complicated lecture about markets. A short conversation about why money can rise and fall, and why investing is not the same as keeping cash, is more useful than simply showing a balance.
This is where the product’s design idea has real value. Children and teens can hear financial terms in school or online, but those ideas often remain abstract. A family investing plan gives the discussion a concrete reference point. I found that the strongest use case is not checking the app repeatedly; it is using the app as a prompt for a consistent conversation.
For a busy household, I would attach the review to an existing routine rather than create a new daily obligation. A Sunday planning session, a monthly family budget check, or a regular allowance discussion can all work. The goal is consistency, not constant monitoring. Looking at investment movement every day could encourage the wrong lesson, especially for a young user who interprets every change as success or failure.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Parents should also decide how much control the child receives in the conversation. A younger child may benefit from simple explanations and a visible goal, while a teenager may want to understand why an adult makes certain decisions. The app can support that progression, but it cannot replace the parent’s judgement about age, maturity, or family circumstances.
The first setup should be treated as a teaching decision
During setup, I would avoid rushing through every choice just to reach the main screen. The important work is defining the purpose of the plan and agreeing on the language the family will use. For example, “this is money for a long-term goal” is clearer than presenting investing as a way to make money quickly.
That framing is one of the less obvious strengths of a child-oriented investing app. A general investing app usually assumes the account holder already understands the basics. Acorns Early has a more natural place in a parent-and-child discussion, even though the adult still needs to explain the risks and limits. If you are hoping the app will independently teach your child what diversification, volatility, or time horizon mean, you may find the experience incomplete without your own guidance.
Another useful habit is to separate the app review from ordinary spending decisions. A child should not automatically connect a short-term purchase with a long-term investment balance. I would keep the conversation focused: spending money is for immediate choices, saving is for a near-term target, and investing is generally associated with a longer horizon. That three-part comparison helps prevent the common mistake of treating every account as interchangeable.
Settings worth checking before building momentum
Experienced users should slow down around the plan settings and review them with the child’s situation in mind. The right configuration is not necessarily the most ambitious one. A contribution or investing habit that fits comfortably into the family budget is more educationally useful than a larger commitment that becomes stressful or gets abandoned.
I would also check who is expected to make decisions and how often the family wants to review them. If the parent is responsible for the plan, the child should understand that participation does not mean unrestricted control. That boundary is especially important with teenagers, who may be ready to learn more but still need an adult to oversee financial choices.
The app’s age positioning makes flexibility important. A plan that works for a young child may need a different explanation for a teenager. With a younger user, I would emphasize goals and patience. With an older user, I would discuss uncertainty, long-term growth, and why a falling value does not automatically mean something has gone wrong. The same screen can support both conversations, but the teaching approach has to change.
Notifications and review habits deserve attention as well. If the app encourages frequent checking, I would resist turning that into a constant market-watching routine. A scheduled review is usually healthier than reacting to every movement. This is a concrete trade-off: visibility can make the plan feel engaging, but too much attention can make long-term investing feel like a short-term game.
I would also prepare a simple family rule for additional money. If a child receives a gift or earns money, decide in advance whether some portion goes toward spending, saving, or the investing plan. The exact split should reflect your household rather than a universal formula. What matters is that the decision is repeatable and explained, so the child sees a process instead of a random transfer.
Faster patterns that reduce family friction
The quickest way to make Acorns Early useful is to remove unnecessary decisions from each review. Choose one regular day, one short explanation format, and one goal that the child can understand. This turns the app from something the family remembers occasionally into a small, dependable part of the week or month.
I would keep a short list of questions nearby: What is this money for? Is the goal short term or long term? What changed since the last review? What do we understand, and what should we look up before making a decision? These prompts prevent the conversation from becoming a vague glance at a number.
A second efficient pattern is to use the app alongside a simple household note. The note can record the child’s goal, the date of the last review, and the question they want answered next time. This is not a replacement for the app; it is a way to preserve the learning around it. It also helps parents avoid repeating the same explanation or forgetting why a particular plan was chosen.
For teenagers, I would invite them to explain the plan back to me. Asking a child to describe what the account is intended to do reveals whether they understand the difference between investing and spending. It also exposes assumptions that might otherwise remain hidden, such as believing that an investment balance should always increase or that a named goal guarantees a particular result.
Families can also make the review more concrete by comparing the investing plan with an ordinary savings goal. The point is not to declare one option better. It is to show that different goals need different tools. Money needed soon should not be discussed in exactly the same way as money intended for a distant future. This comparison is one of the most valuable uses of the app because it teaches selection, not just participation.
Where the app is stronger than ordinary alternatives
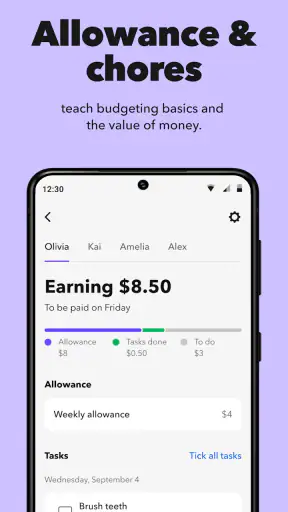
Compared with a basic allowance tracker, Acorns Early offers a more direct connection to long-term investing. An allowance app may be better for chores, spending records, or short-term rewards, but it may not create the same opportunity to discuss market uncertainty and patience. If your main goal is teaching a child to divide pocket money, a simple tracker could be easier and less serious.
Compared with a standard adult investing app, this product is more naturally suited to a family conversation. Adult platforms often present research, charts, and choices that can overwhelm a young user or make the parent do all the explaining. Acorns Early’s child-and-teen focus gives the household a clearer reason to sit together, even though it does not remove the need for adult supervision.
There is also a middle ground. Some families may prefer a bank account for near-term saving and use this app only for the long-term portion of a child’s financial education. That combination can be more realistic than expecting one product to handle spending, saving, investing, and lessons equally well. I would not use Acorns Early as the only money tool if the family also needs detailed budgeting or everyday payment management.
Limits that become clearer with advanced use
The biggest limitation is that a smart investing plan can sound more automatic than it really is. The app may help organize the experience, but a parent still has to choose appropriate goals, explain risk, and decide how much attention the plan deserves. The word “smart” should not be interpreted as “self-managing” or “guaranteed.” That distinction should be made clear to both parent and child.
Another limitation is the emotional difficulty of teaching investing honestly. Children may enjoy seeing progress but become discouraged when the value moves in the other direction. If your child is likely to worry about fluctuations, an ordinary savings approach may be a better first step. The app is not wrong for that child; the timing or teaching context may simply be wrong.
Parents should also consider whether they want a financial education tool or a hands-on investing platform. Those are related but different needs. Acorns Early is appealing when the family wants a guided structure around a child’s long-term plan. It is less suitable for someone looking for detailed trading controls, extensive analysis, or a professional research workspace.
Privacy and responsibility should be part of the family discussion too. A child-oriented finance app naturally involves an adult managing important information and decisions. I would read the app’s current account and privacy explanations carefully before committing, then explain to the child why some actions remain restricted to the parent. That conversation reinforces a useful lesson: access to financial information and responsibility for financial decisions are not always the same thing.
Who should use it, and who should choose something else?
I think Acorns Early is a good fit for parents who want to introduce investing gradually, prefer a guided family routine, and are willing to explain what the child sees. It is particularly useful when the family has a clear long-term purpose and wants the child to understand that money can be assigned different jobs.
It is less convincing for parents who only need chore tracking, a spending wallet, or a basic savings jar. It may also be a poor match for families seeking complete control over every investment choice or a detailed financial dashboard. In those cases, an adult-oriented brokerage or a simpler banking product may be more appropriate, depending on the goal.
The app is free to install, which lowers the barrier to trying its approach. Still, “free” should not be confused with “no financial consequences.” Any investing decision deserves the same care as it would outside a child-focused interface. I would explore the setup, read the relevant terms, and decide whether the plan fits the household before presenting it as a commitment to the child.
My verdict after using the workflow as intended
Acorns Early earns its place when it is used as a bridge between a parent’s financial responsibility and a child’s growing understanding. Its strongest feature is not simply putting an investing plan in a younger person’s context. It is giving families a reason to create a repeatable conversation about goals, patience, and uncertainty.
The average rating is 4.5 from around 3.2 thousand ratings, and the app has passed 100 thousand installs. Those figures suggest a solid level of interest, but I would judge it by fit rather than popularity. A parent who wants a simple, structured starting point may find it approachable. A user expecting a complete money-management system may feel that it is too focused.
My recommendation is to start with one modest goal, one scheduled review, and one clear explanation of what investing can and cannot do. Check the settings before creating momentum, avoid turning balance changes into daily entertainment, and use the app to compare long-term investing with ordinary saving. The best results come from the family habit around the app, not from opening it more often.
With that mindset, this finance app is a useful introduction for kids and teens, especially when the adult remains present and honest about risk. I would recommend it to families ready to teach through regular practice. I would skip it in favor of a simpler alternative if the immediate need is spending control, allowance tracking, or short-term saving rather than a guided investing conversation.
Frequently Asked Questions
01What is Acorns Early: Kids Money App, and who is it designed for?
Acorns Early: Kids Money App is a family-focused financial education and money management tool designed to help children learn about saving, spending, and earning under parental guidance. Parents typically create and manage the child’s experience, while kids can use age-appropriate features to understand everyday money decisions. Availability, features, and eligibility may depend on the child’s age, account type, and the country where the service is offered.
02Is Acorns Early: Kids Money App safe for children to use?
The app is intended to provide a supervised environment rather than unrestricted financial access. Parents remain responsible for setting up the account, reviewing activity, and explaining how money features work. Before downloading, guardians should check the current privacy policy, parental controls, permissions, and account requirements. It is also important to discuss online safety with children and avoid sharing passwords, PINs, or personal information.
03Does Acorns Early help children save or invest real money?
Acorns Early may connect a child’s money experience with parent-managed saving or investing features, depending on the specific product and eligibility rules. This does not mean children independently control an investment account. Parents should carefully review fees, account ownership, transfer rules, tax considerations, and investment risks before activating any financial feature. Investment values can rise or fall, so the app should support education rather than promise guaranteed growth.
04Can parents control what their children do in Acorns Early?
Parental involvement is central to the app’s design. Depending on the available version, parents may be able to review activity, manage permissions, establish goals, monitor money-related actions, or oversee linked accounts. Controls can vary by plan and region, so families should inspect the settings after installation. Parents should also regularly review notifications and transactions instead of assuming that the initial setup provides complete supervision.
05Is Acorns Early: Kids Money App free to download and use?
The app may be free to download, but some services can require an eligible Acorns account, a subscription, or other paid plan. Financial products may also have separate fees, minimum requirements, or restrictions that are not obvious from the app-store listing alone. Before signing up, read the latest pricing information and terms carefully, and confirm whether the features you want are available in your location and on your device.


